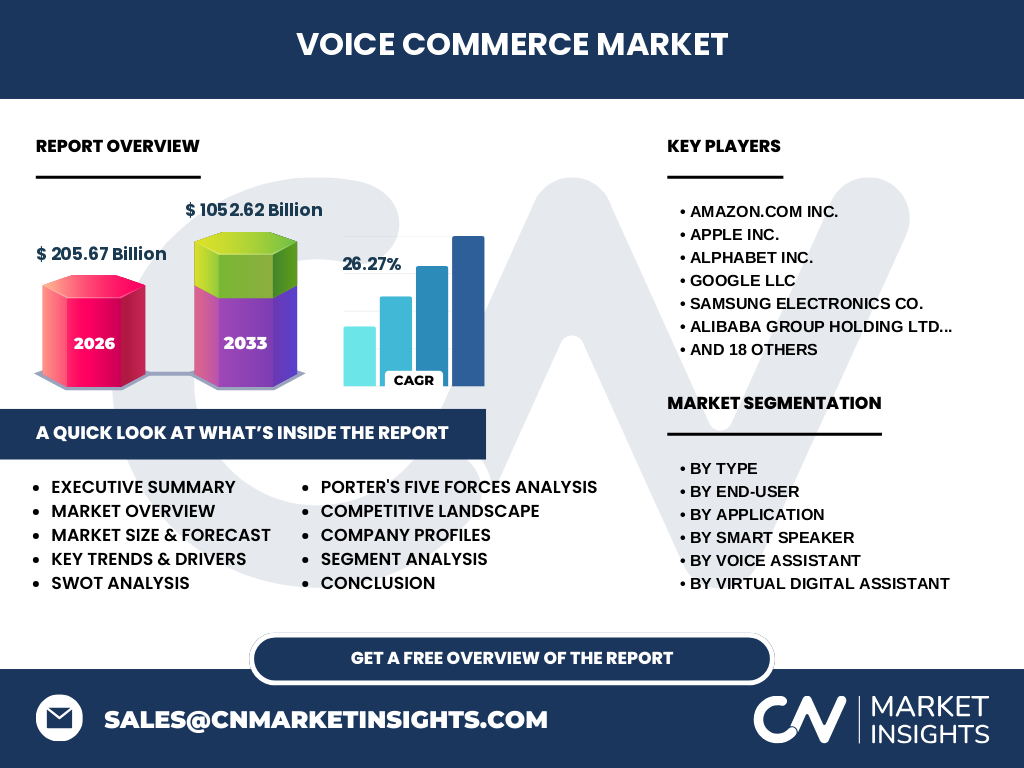
Market overview of the Voice Commerce Market
Our analysis indicates that the Voice Commerce Market represents a transformative economic shift, valued at 205.67 Billion in 2026. This ecosystem encompasses transactional voice interactions via smart speakers, virtual assistants, and dedicated AI models, redefining how consumers purchase electronics, groceries, and personal care items globally.
Structural Growth Drivers and Market Restraints
Growth is accelerated by consumer demand for frictionless retail, while stringent data privacy regulations by bodies like the FTC and EU GDPR act as key restraints. Logistics hurdles in last-mile grocery fulfillment further challenge supply chains, though advancements in NLP by Amazon.com Inc. and Alphabet Inc. mitigate these barriers.
Emerging trends and growth patterns in Voice Commerce Market
The data suggests a rapid evolution toward multimodal interfaces combining voice commands with visual displays. Consumers increasingly utilize devices powered by Apple Inc. and Google LLC for routine household appliance replenishment and complex travel bookings, driving high-frequency transactional engagement.
COVID-19 impact analysis and recovery trajectory
The pandemic drastically accelerated contactless retail adoption, pushing touch-free voice interactions into the mainstream. As physical retail faced lockdowns, platforms integrated by Alibaba Group Holding Ltd. and Baidu Inc. captured surging online demand, cementing a robust post-pandemic recovery trajectory centered on automated home shopping.
Competitive landscape and strategic market concentration
Market concentration remains high, dominated by tech titans controlling proprietary hardware and assistant ecosystems. Amazon.com Inc. leverages its Echo lineup for retail dominance, while Samsung Electronics Co. and Sony Corp. embed voice tech across diverse consumer electronics to capture fragmented market share.
Executive summary of key findings
Our comprehensive research confirms the Voice Commerce Market industry trends point toward unprecedented expansion, reaching 1052.62 Billion by 2033 at a CAGR of 26.27%. Stakeholders must prioritize AI integration and localized language processing to capitalize on this exponential revenue trajectory.
Market forecast from 2027 to 2033
Driven by compounding adoption rates across emerging economies, the sector is projected to scale from its 2026 baseline to 1052.62 Billion by 2033. This trajectory reflects a formidable 26.27% CAGR, fueled by deeper integration of generative AI within virtual digital assistants.
Segmentation analysis across types, end-users, and applications
Segmentation spans types including Smart Speaker (Amazon Echo, Google Home, Apple HomePod), Voice Assistant (Google Assistant, Amazon Alexa, Apple Siri, Microsoft Cortana), and Virtual Digital Assistant. End-users comprise the Travel, Hospitality, and Entertainment industries, while applications cover Groceries, Electronics, Household Appliances, Personal Care, and Arts Crafts.
Regional market analysis and geographic distribution
Geographic performance is heavily weighted toward North America and Asia-Pacific, driven by high smart speaker penetration and advanced telecommunications infrastructure. Localized regulatory frameworks and varying consumer trust levels heavily influence adoption speeds across European Union member states and Latin American markets.
In-depth regional review of key markets
North America leads in transaction volume due to high early adoption of devices by Sonos Inc. and Vizio Inc. Meanwhile, Asia-Pacific exhibits the fastest growth, propelled by mobile-first ecosystems managed by Alibaba Group Holding Ltd. and Baidu Inc. navigating distinct regional logistical networks.
Company profiles and strategic positioning
Industry leaders like Microsoft Corp., Salesforce Inc., and Twilio Inc. provide enterprise-grade conversational AI infrastructure. Meanwhile, specialized innovators like SoundHound Inc., Voicify LLC, and Jetson AI Inc. offer bespoke voice applications that enhance brand-specific retail touchpoints.
Porter's Five Forces analysis of the sector
Competitive rivalry is intense among major platform owners, while the threat of new entrants is tempered by high R&D costs for natural language processing. Bargaining power of buyers remains moderate, constrained by ecosystem lock-in fostered by giants like Apple Inc. and Google LLC.
SWOT analysis of the Voice Commerce Market
Key strengths include unmatched user convenience and rapid AI processing. Weaknesses involve audio misinterpretations and payment security concerns. Opportunities lie in emerging IoT home integrations, while threats include evolving cybersecurity regulations and potential consumer pushback regarding voice data harvesting.
Value chain analysis from raw materials to end-users
The value chain initiates with raw semiconductor materials and acoustic hardware components, progressing to software development by firms like Nuance Communications. It culminates in cloud hosting by Alphabet Inc. and transactional execution via platforms like BigCommerce Pty. Ltd. for end-consumers.
Investment insights and strategic high-potential areas
Investors should target niche voice optimization startups and multilingual NLP developers that reduce transactional friction. Partnerships with hospitality platforms, such as integrations utilized by Ferns N Petals Pvt. Ltd. or Humanize LLC, present lucrative avenues for high-margin B2B deployments.
Conclusion and key takeaways for stakeholders
The Voice Commerce Market analysis demonstrates that voice-enabled transactions are transitioning from novelty features to core retail revenue channels. Achieving market leadership requires aligning hardware ecosystems with secure, AI-driven conversational commerce strategies to capture the forecasted 1052.62 Billion valuation.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining global trade registry data, primary stakeholder interviews with executives from Lenovo Group Ltd., HP Inc., and LG Electronics, and secondary macroeconomic indicators to ensure high statistical fidelity across all market segments.
Scope of the report and coverage parameters
This report covers global revenue estimations from 2026 to 2033, evaluating hardware shipments, software licensing, and direct transactional volumes. Limitations include exclusion of unregistered peer-to-peer voice transactions and localized black-market retail channels operating outside standard regulatory oversight.
Recent developments, partnerships, and strategic moves
Recent industry momentum features collaborative product launches and strategic acquisitions, such as enhanced voice-shopping integrations by iAdvize Inc. and expanded smart-display capabilities from Amazon.com Inc. and Google LLC, designed to streamline checkout workflows and bolster enterprise conversion rates.